

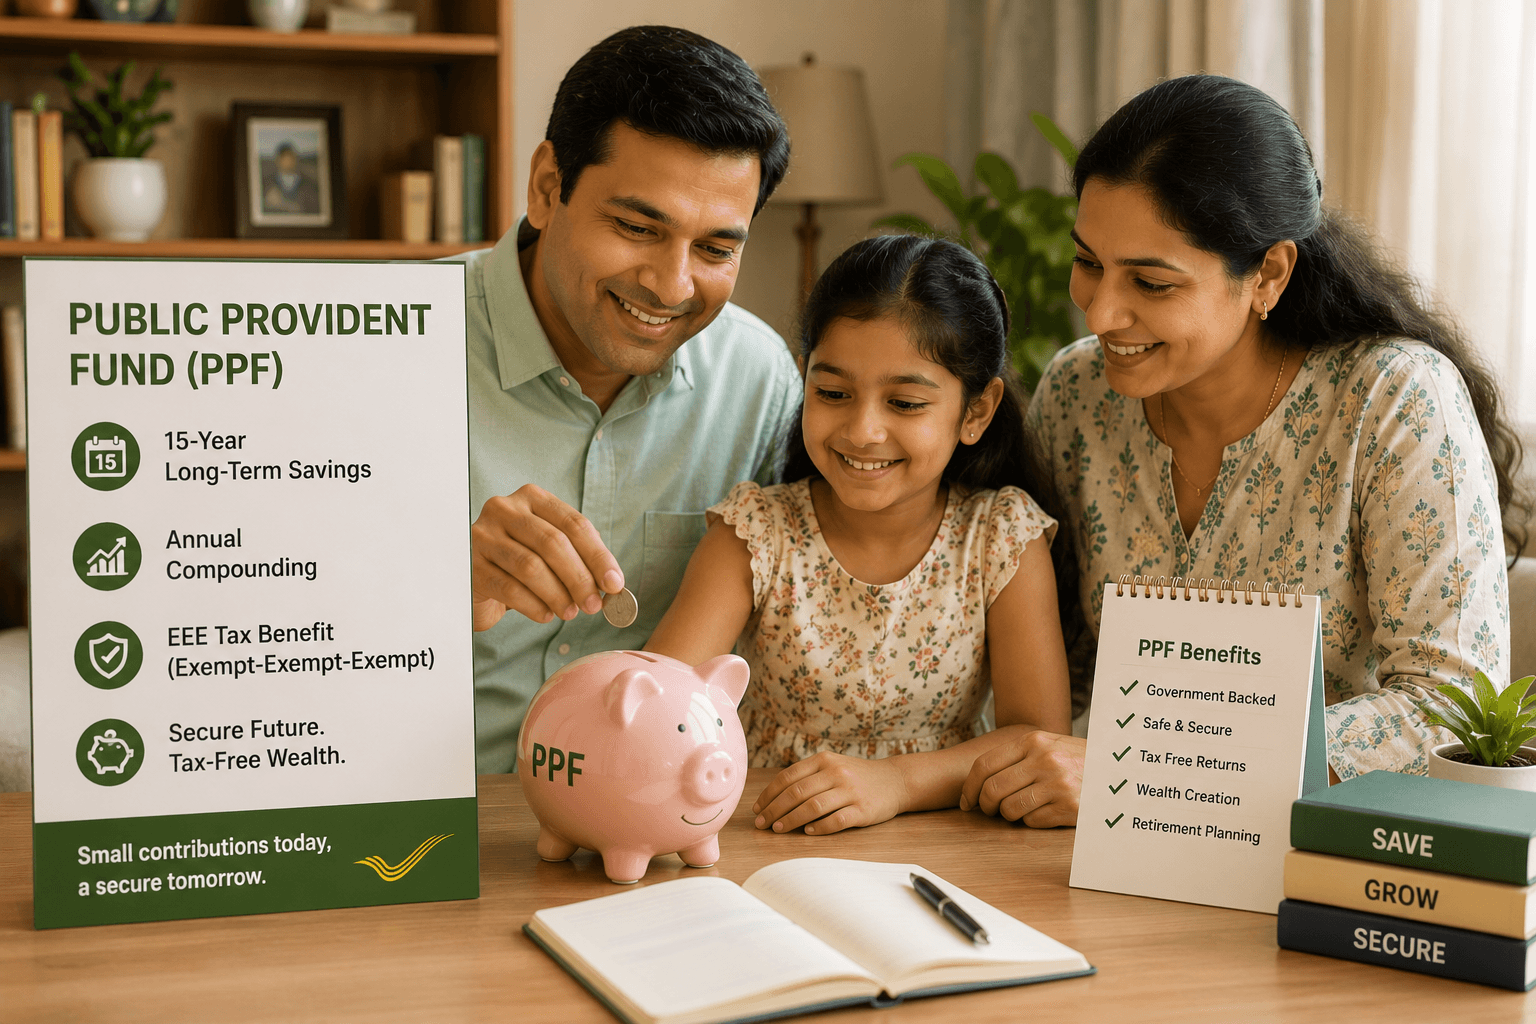
Long-Term Wealth · EEE Tax Status
Public Provident Fund (PPF)
India's most popular long-term savings scheme — government-backed, annually compounded, and fully tax-exempt at every stage: investment, interest, and maturity.
Govt-Backed
Sovereign guarantee — one of India's safest savings options.
EEE Tax Status
Invest, interest, and maturity — all potentially tax-exempt.
15-Year Growth
Annual compounding builds a substantial corpus over time.
Loan Facility
Borrow against your balance from year 3 to year 6.
Partial Withdrawal
Withdraw a portion from the 7th financial year onwards.
Overview
What is PPF?
The Public Provident Fund (PPF) is a Government of India-backed long-term savings scheme with a 15-year tenure, annual compounding, and a rare EEE (Exempt-Exempt-Exempt) tax status — meaning your contributions, the interest earned, and the maturity amount are all potentially tax-exempt. It's one of the most effective tools for long-term wealth creation and retirement planning available to resident individuals.
Why PPF's Tax Status is Special
01
Invest
Up to ₹1.5L/year qualifies for Section 80C deduction.
02
Interest
Annual interest is exempt from income tax.
03
Maturity
The full maturity amount is tax-free on withdrawal.
* Tax treatment is subject to applicable laws and the investor's individual circumstances. Verify with your tax advisor.
Contribution Rules
How Much Can You Invest?
Minimum / Year
₹500
to keep account active
Maximum / Year
₹1.5L
single + minor's account combined
Payment Mode
Lump sum or installments
any number during the year
The ₹1.5L annual cap includes deposits made by the account holder in both their own account and any minor's account they manage, per applicable scheme rules.
Eligibility
Who Can Open a PPF?
- Any eligible resident individual (one account per person)
- Parent or legal guardian may open on behalf of a minor
- Joint accounts are not permitted under PPF
- HUFs cannot open a new PPF account
- NRIs cannot open a new PPF account
KYC
Documents Required
- Identity proof — Aadhaar, PAN, Passport, Voter ID
- Address proof as per applicable KYC norms
- PAN card or Form 60 (where applicable)
- Photograph if required by the bank or Post Office
- PPF account opening form or digital application
- Minor's account: additional documents for minor and guardian
Liquidity Features
Loan & Partial Withdrawal
Loan facility
You can take a loan against your PPF balance from the 3rd financial year up to the end of the 6th financial year, subject to applicable limits and conditions. The loan must typically be repaid before a second loan can be taken.
Partial withdrawal
Partial withdrawals are permitted from the 7th financial year onwards, subject to the prescribed limits under the PPF Scheme rules. Only one partial withdrawal is generally allowed per financial year.
Where to Open
Post Offices & Authorised Banks
- Designated Post Offices across India
- Authorised public and private sector banks
- Online via internet or mobile banking (most authorised banks)
Most authorised banks let you open and manage your PPF account entirely online. Existing savings account holders can often link their PPF account for easy annual deposits.
India Post Savings Schemes →After 15 Years
What Happens at Maturity?
- Withdraw the full balance and close the account
- Extend for a block of 5 years with continued contributions
- Extend without further contributions and earn interest on existing balance
Extensions are in blocks of 5 years — there is no limit on the number of extensions. Each extension must be applied for within one year of the maturity date, subject to applicable procedures.
Things to Know
Before You Invest
- 15-year lock-in — not suitable as an emergency or short-term fund
- Minimum ₹500/year must be deposited to keep the account active
- Deposits above ₹1.5L/year earn no interest and attract no 80C benefit
- Interest rate is reviewed quarterly — not guaranteed for the full 15 years
- NRIs and HUFs cannot open a new PPF account
- Do not rely solely on PPF for liquidity — access is restricted
Want to know how PPF fits your long-term plan?
Talk to a Wealth Doctor — free advice.