

Agriculture Finance · Farmer Credit · Allied Activities
Kisan Credit Card (KCC)
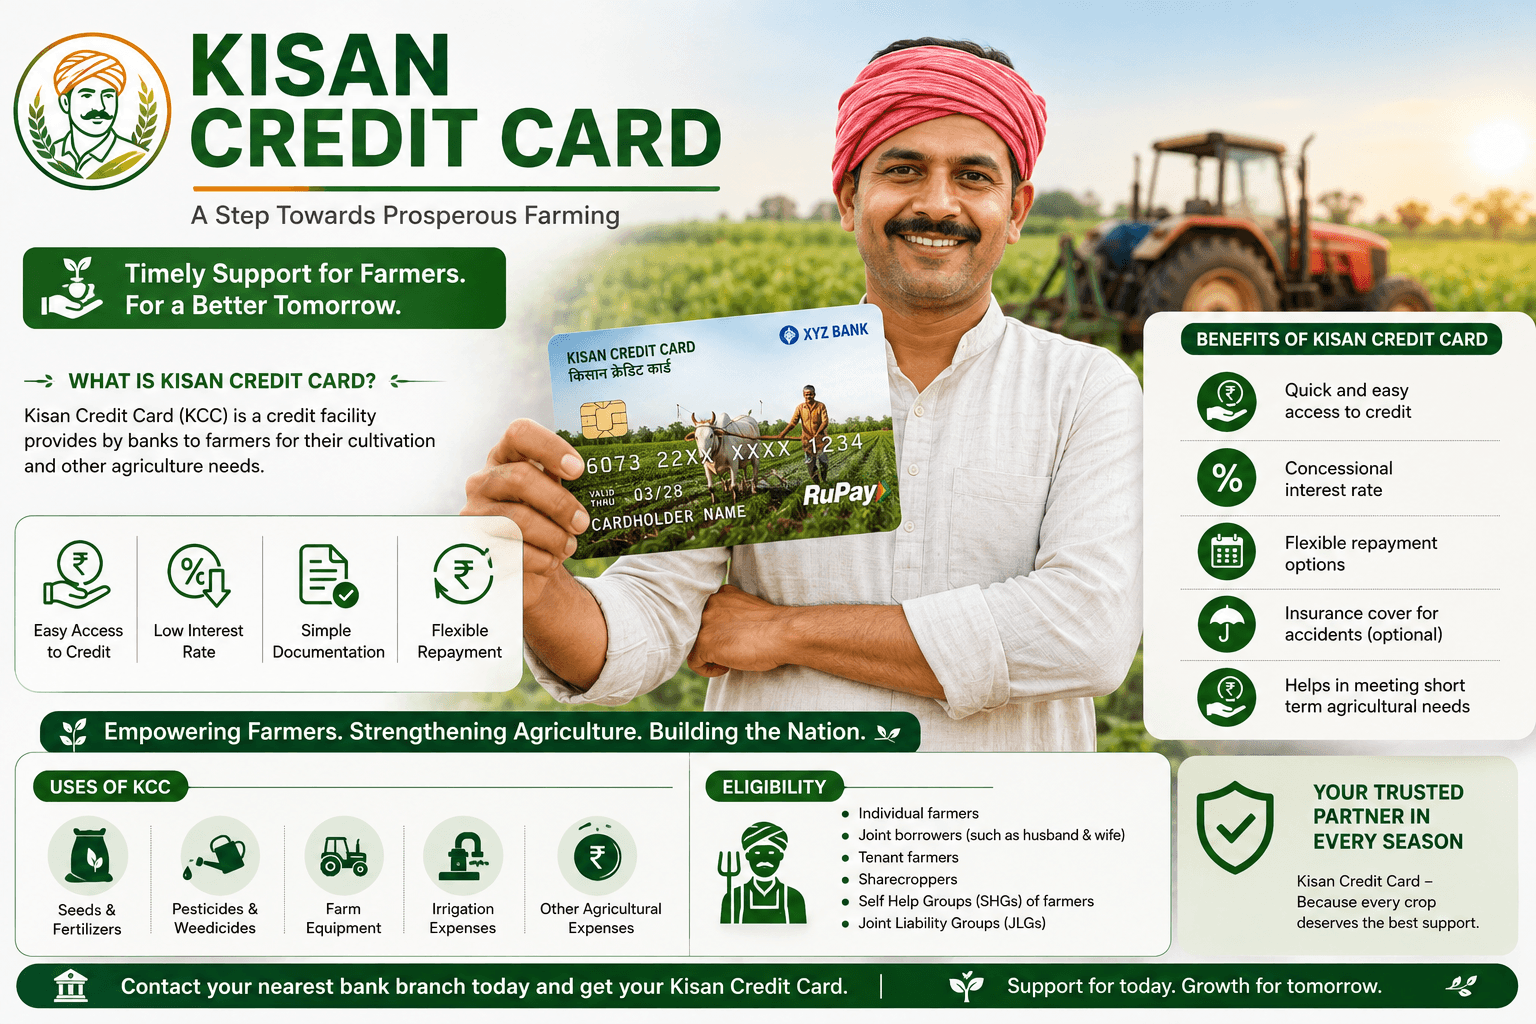
A flexible institutional credit facility designed to provide farmers with timely and affordable credit for crop cultivation, post-harvest expenses, farm maintenance and eligible allied activities.
Flexible Credit
Access credit within the sanctioned limit based on eligible agricultural and allied activity requirements.
Farm Finance
Supports crop cultivation, inputs, post-harvest expenses, farm maintenance and other eligible needs.
Allied Activities
Coverage extends to eligible dairy, animal husbandry and fisheries-related working capital.
Collateral-Free
Eligible agricultural loans up to ₹2 lakh can be provided without collateral, subject to applicable guidelines.
Revolving Credit
Subject to facility terms, borrowers can draw and repay funds within the approved credit limit.
Overview
What is a Kisan Credit Card?
The Kisan Credit Card (KCC) is a credit facility designed to provide farmers with timely and affordable institutional credit for agriculture and allied activities.
The scheme was introduced in 1998 and has since been expanded to cover a wider range of agricultural and allied financing requirements.
KCC provides farmers with a simplified and flexible credit facility for crop cultivation, post-harvest expenses, working capital, allied activities and certain investment requirements, subject to applicable banking and scheme guidelines.
Purpose
What Can KCC Credit Be Used For?
Crop Cultivation
Short-term credit for cultivation of crops and related agricultural requirements.
Agricultural Inputs
Purchase of inputs such as seeds, fertilisers and pesticides.
Post-Harvest Expenses
Credit support for eligible expenses after harvesting and during produce handling.
Produce Marketing
Financing for eligible requirements associated with marketing agricultural produce.
Farm Asset Maintenance
Working capital for maintenance of farm assets and related agricultural needs.
Allied Agricultural Activities
Working capital for eligible allied agricultural activities.
Household Consumption
Consumption requirements of farmer households, subject to the applicable KCC framework.
Investment Credit
Investment credit for agriculture and allied activities, where applicable.
KCC coverage has also been expanded to include working capital requirements for animal husbandry, dairy and fisheries.
Eligibility
Who Can Apply?
The following categories may be eligible for a Kisan Credit Card, subject to the lending institution's assessment and applicable guidelines.
- Individual farmers who are owner cultivators
- Joint borrowers who are owner cultivators
- Tenant farmers
- Oral lessees
- Sharecroppers
- Self-Help Groups (SHGs) of eligible farmers
- Joint Liability Groups (JLGs) of eligible farmers
- Eligible farmers engaged in agriculture and allied activities
- Eligible fishers and fish farmers
- Eligible dairy and animal husbandry farmers
Final eligibility and credit assessment are determined by the concerned bank or lending institution.
Credit Limit
How Is the KCC Credit Limit Determined?
The KCC credit limit is not the same for every farmer. It is generally determined based on the nature and scale of the agricultural or allied activity and the lending institution's assessment.
Area of Land Cultivated
The cultivated area can form part of the basis for determining the credit requirement.
Cropping Pattern
The type and pattern of crops being cultivated may affect the applicable credit limit.
Scale of Finance
The scale of finance fixed for the relevant crop is considered in determining eligible credit.
Cost of Cultivation
Estimated cultivation costs can influence the amount of credit required.
Post-Harvest Requirements
Post-harvest and farm maintenance requirements may form part of the credit assessment.
Working Capital Needs
Working capital requirements for agriculture and eligible allied activities may be considered.
Investment Requirements
Eligible investment requirements may be considered where applicable.
Repayment Capacity
The borrower's ability to repay the facility is considered by the lending institution.
Under the current framework, the Modified Interest Subvention Scheme (MISS) has been enhanced to ₹5 lakh.₹5 lakh.
Important — Collateral
Collateral-Free Credit Up to ₹2 Lakh
The collateral-free agricultural loan limit has been increased to ₹2 lakh per borrower, effective from 1 January 2025, subject to applicable lending and regulatory guidelines.
The updated limit is intended to improve access to institutional credit, particularly for small and marginal farmers and other eligible borrowers.
Interest Rate
Interest Rate & Interest Subvention
KCC interest rates depend on the type of loan, loan amount and applicable government schemes.
Applicable Short-Term Loans
7%
7% per annum for eligible short-term agricultural loans up to ₹3 lakh under MISS, subject to scheme conditions.
Prompt Repayment Incentive
Up to 3%
Available to eligible borrowers who repay qualifying loans on time.
Effective Rate
4%
Potential effective rate for eligible borrowers after the applicable repayment incentive.
The enhancement of the overall MISS lending limit to ₹5 lakh does not mean that every KCC loan up to ₹5 lakh automatically receives the 4% effective rate. Eligibility depends on prevailing scheme conditions and the type of eligible loan.
Validity & Renewal
How Long Is a KCC Valid?
A KCC is generally structured as a revolving credit facility and may have a validity period of up to five years, subject to periodic review and the lending institution's policies.
Repayment
Repayment Period
The repayment period depends on the type of credit facility and the nature of the agricultural or allied activity.
- Crop Loans — Generally aligned with the crop cycle, harvesting period and marketing of produce.
- Allied Activity Working Capital — May depend on the income cycle of the relevant activity.
- Term & Investment Credit — Determined based on the asset financed, expected cash flow and lender assessment.
Key Features
Why Is the Kisan Credit Card Useful?
Flexible Credit Facility
Access credit within the sanctioned limit based on agricultural and allied activity requirements.
Single-Window Credit
Can cover crop production, post-harvest expenses, farm maintenance and eligible allied activities.
Revolving Credit
Subject to facility terms, borrowers can draw and repay funds within the approved credit limit.
Affordable Credit
Eligible short-term agricultural loans may receive interest support under MISS.
Prompt Repayment Benefit
Eligible farmers who repay qualifying loans on time may receive the Prompt Repayment Incentive.
Collateral-Free Credit
Eligible agricultural loans up to ₹2 lakh can be provided without collateral, subject to applicable guidelines.
Allied Activity Coverage
KCC coverage extends to eligible dairy, animal husbandry and fisheries activities.
Digital Access
Banks and financial institutions increasingly offer digital application and processing facilities.
Application
How to Apply for a Kisan Credit Card
Eligible farmers can generally apply through participating lending institutions, including:
Digital Application
Applications may be submitted through bank branches, while some banks provide online or digital application facilities. The JanSamarth platform and other digital banking channels may also support access to eligible credit schemes.
Documentation
Documents Required
Documentation requirements can vary depending on the bank, borrower category and nature of the agricultural activity.
Tenant farmers, sharecroppers and group borrowers may need to provide alternative or additional documentation according to the bank's policies and applicable guidelines.
Digital Initiatives
Making KCC Access More Digital
The Government has introduced digital initiatives to improve KCC access and monitoring.
Kisan Rin Portal
Supports digital integration of farmer profiles, loan information, interest subvention claims and scheme monitoring.
Digital Banking & CSCs
Digital channels and Common Service Centres can help improve access and reduce processing delays in applicable cases.
Due Diligence
Points to Consider Before Applying
Assess Your Credit Requirement
Borrow according to your genuine crop, farm or allied activity requirements.
Understand the Credit Limit
The sanctioned limit depends on the scale of finance, cultivated area, activity and lender assessment.
Check Interest Benefits
Confirm whether your loan qualifies for interest subvention and the Prompt Repayment Incentive.
Understand the Repayment Schedule
Ensure repayment is planned according to your crop cycle or business cash flow.
Maintain Good Repayment Behaviour
Timely repayment may help you qualify for applicable interest benefits and support future credit requirements.
Check All Charges
Ask the bank about applicable processing charges, insurance, documentation charges or other fees.
Use Credit for the Approved Purpose
KCC funds should be used for the sanctioned agricultural or allied activity requirements.
Review the Terms Carefully
Read the sanction letter and loan agreement before accepting the facility.
Current KCC Highlights
KCC in Numbers
Active KCC Accounts
7.72 Crore+
As reported by the Government in March 2026
Outstanding Loans
₹10.2 Lakh Crore
Approximately, as reported in March 2026
The KCC ecosystem continues to cover farmers as well as eligible borrowers engaged in allied activities such as dairy, animal husbandry and fisheries.
Things to Know
Before Accepting a KCC Facility
- Confirm the sanctioned credit limit based on your crop, cultivated area or eligible allied activity
- Check whether the loan qualifies for interest subvention and the Prompt Repayment Incentive
- Understand the repayment schedule according to your crop cycle or activity income cycle
- Ask the bank about applicable processing, insurance, documentation or other charges
- Use KCC funds only for the sanctioned agricultural or allied activity requirements
- Maintain timely repayment to support applicable interest benefits and future credit requirements
- Read the sanction letter and loan agreement carefully before accepting the facility
- Verify the latest terms with the concerned bank or official government sources
Conclusion
Making an Informed KCC Decision
The Kisan Credit Card provides farmers with access to timely institutional credit for agriculture and allied activities and can support crop production, post-harvest expenses, working capital and eligible investment requirements.
Under the current framework, the MISS lending limit has been enhanced to ₹5 lakh, while the collateral-free agricultural loan limit is ₹2 lakh per borrower, subject to applicable guidelines.
Eligible short-term agricultural loans may also receive concessional interest support, with timely repayment potentially reducing the effective interest rate to 4% per annum under the applicable scheme conditions.
Disclaimer
Eligibility, credit limits, interest rates, interest subvention, repayment terms, documentation and other conditions may vary based on the type of loan, borrower profile, lending institution and prevailing government or RBI guidelines. Applicants should verify the latest terms with the concerned bank or official government sources before applying.
Have questions about a Kisan Credit Card?
Talk to a Wealth Doctor — free advice.