

Group Protection · Accident Cover · Employee Benefits
Group Personal Accident Insurance
Financial protection for eligible group members against specified consequences of accidental bodily injury.
Accidental Death
Financial support for nominees.
Group Coverage
Members covered under one policy.
Disability Benefits
Support for covered disabilities.
Employee Welfare
Added financial protection.
Overview
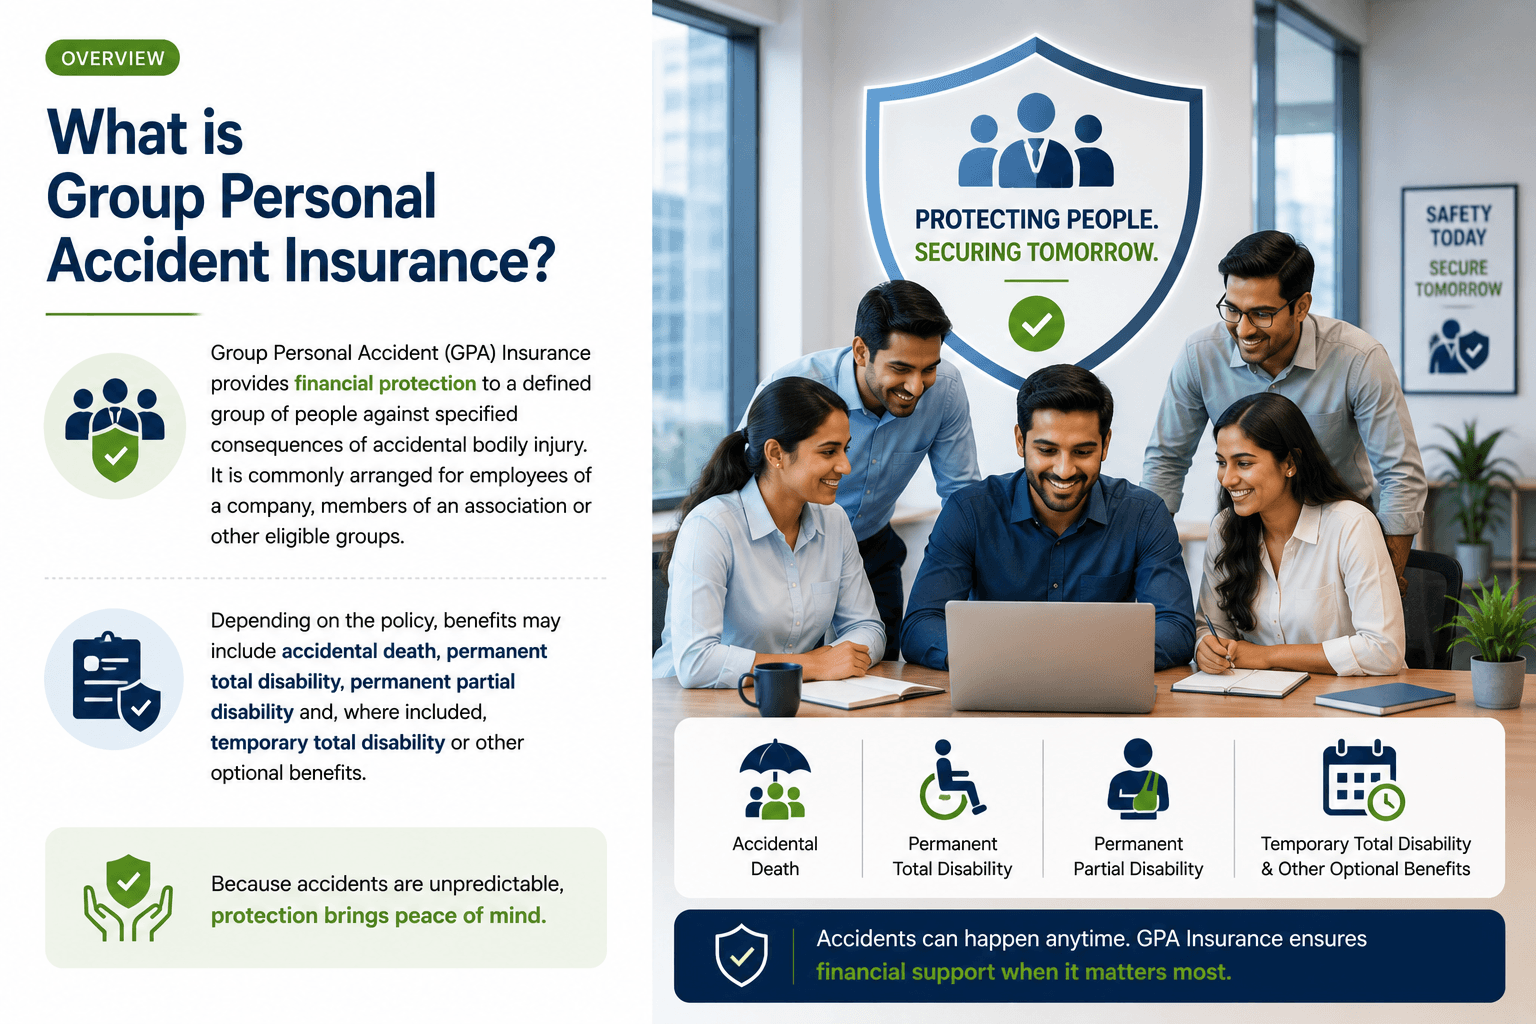
What is Group Personal Accident Insurance?
Group Personal Accident (GPA) Insurance provides financial protection to a defined group of people against specified consequences of accidental bodily injury. It is commonly arranged for employees of a company, members of an association or other eligible groups.
Depending on the policy, benefits may include accidental death, permanent total disability, permanent partial disability and, where included, temporary total disability or other optional benefits.
Why Consider
Why Choose Group Personal Accident Insurance?
- Provides financial protection against covered accidental death or disability
- Can form part of an employee benefits and welfare programme
- Sum insured and benefit structures may be customised for the group
- A group arrangement can simplify accident insurance administration
- Group pricing may be competitive depending on the group's risk profile
Eligibility
Who Can Benefit from Group Personal Accident Insurance?
- Employees of a company or organisation
- Members of eligible associations
- Professional bodies and other qualifying groups
- Eligible organisation members
- Families and nominees of insured members
Eligibility, occupations covered, group size and other conditions depend on the insurer and the specific group policy.
Key Benefits
Benefits of Group Personal Accident Insurance
- Accidental death benefit payable according to policy terms
- Permanent total disability benefit for covered conditions
- Permanent partial disability benefit according to the policy schedule
- Temporary total disability benefits where specifically included
- Optional benefits may include accidental medical expenses, ambulance expenses, fractures or other specified benefits
- Coverage scope depends on the policy wording and certificate of insurance
Financial Protection
Accident Benefits for Members and Nominees
If an insured person dies or suffers a covered disability as a result of an accident, the applicable benefit may be payable according to the policy terms and claim conditions.
Accidental Death
Permanent Disability
Family Financial Support
Group Coverage
How Group Personal Accident Insurance Works
Master Policyholder
Employer or eligible organisation arranges the group policy.
Insured Members
Eligible employees or group members receive accident coverage.
Nominee or Beneficiary
The applicable death benefit is paid according to the policy terms.
Buying Guide
Where Can One Obtain Group Personal Accident Insurance?
- Insurance companies registered and authorised to conduct insurance business in India
- Licensed insurance agents or intermediaries
- Authorised insurance distribution channels
Employers and organisations should verify that the insurer or intermediary is appropriately authorised before arranging coverage.
Risk Profile
Occupation and Accident Risk Matter
The type of work performed by employees can affect underwriting, premiums, eligibility and coverage terms. Higher-risk occupations may require different terms or additional underwriting.
Coverage Scope
Check the Exact Coverage Period and Area
Some policies may provide 24-hour protection or coverage while travelling, while others may contain occupational, geographical or activity-based restrictions. The actual scope should be confirmed in the policy wording.
Important
GPA Is Not Automatically a Replacement for Health Insurance
Group Personal Accident Insurance is primarily designed to provide benefits for accidental death or specified disabilities. Hospitalisation or accidental medical expense coverage is available only when specifically included in the policy.
Documentation
Documents & Information Required
- Group or organisation details
- Employee or member name and personal details
- Date of birth and occupation information
- Identity and KYC information, where required
- Nominee or beneficiary details
- Medical or underwriting information, where required
- Additional enrolment or policy documents, where applicable
Before Choosing
Things to Consider
- Check whether the sum insured is adequate for the group
- Review the nature of occupations and associated risks
- Understand accidental death and disability benefit amounts
- Read the disability definitions and benefit schedule
- Review exclusions, limitations and hazardous activity restrictions
- Check the geographical and coverage period scope
- Do not assume medical expenses are automatically covered
- Keep employee and nominee records accurate and updated
- Understand the claims process and required documents
- Read the policy schedule, wording and certificate of insurance carefully
Definitions
Understand Disability Definitions and Benefit Schedules
Review how the policy defines an accident, bodily injury, permanent total disability and permanent partial disability. Disability benefits may be payable according to percentages or conditions specified in the policy schedule.
Exclusions
Review Exclusions and Limitations
Carefully review circumstances that may not be covered. Restrictions can vary and may relate to intentional self-injury, hazardous activities, intoxication, criminal acts, pre-existing disabilities or other situations specified in the policy wording.
Claims
Understand the Claims Process
- Know the documents required for a claim
- Understand claim notification timelines
- Keep employee and nominee information accurate
- Know the contact details and procedure for raising a claim
- Review the insurer's claim requirements and policy conditions
Policy Documents
Read the Policy Schedule and Certificate
The policy schedule, wording, certificate of insurance and any endorsements ultimately determine the actual coverage and benefits available to insured members.
Conclusion
A Structured Way to Provide Accident Protection
Group Personal Accident Insurance can be a valuable component of an employee benefits or member welfare programme. It can provide financial support when a covered accident results in death or disability while allowing organisations to structure coverage according to the needs and risk profile of their group.
Benefits such as medical expense reimbursement, temporary disability payments, worldwide coverage, 24-hour protection and additional allowances are policy-specific and should not be assumed to be automatically available.
Need help understanding accident insurance?
Talk to a Wealth Doctor — free advice.